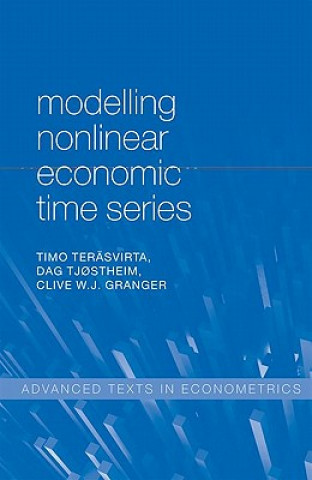
Kód: 04533586
Modelling Nonlinear Economic Time Series
Autor Timo Terasvirta, Dag Tjostheim, Clive W. J. Granger
This book contains an extensive up-to-date overview of nonlinear time series models and their application to modelling economic relationships. It considers nonlinear models in stationary and nonstationary frameworks, and both para ... celý popis


- Jazyk:
 Angličtina
- Vazba: Pevná
- Počet stran: 586
Nakladatelství: Oxford University Press, 2010
- Více informací o knize


Mohlo by se vám také líbit
-
SHOCK DOCTRINE
407 Kč -

Poems of Sappho
150 Kč -

American Gods: The Tenth Anniversary Edition
449 Kč -

Přehledová tabulka učiva – přehled gramatiky pro žáky prvního stupně 1
27 Kč -

Law of Attraction
421 Kč -

NARWHALICORN AND JELLY
197 Kč -

Fuchsian Groups
1090 Kč -
RoboCop Replica 1/1 RoboCop Helmet 43 cm
14357 Kč -

How to Be an Urban Birder
384 Kč -

English for Academic Purposes Practitioner
2923 Kč -

Oxford Handbook of Ancient Greek Religion
5576 Kč -

Los mejores cuentos para niños de León Tolstoi
372 Kč -

On the Trail of John Muir
220 Kč -

Constitutions of the German Empire and German States
720 Kč -

Von Mondlandschaften Zur Vision Eines Neuen Seenlandes
1323 Kč -

Freedom National
712 Kč -

Japan's International Agenda
852 Kč -

Как жить в России и быть здоровым
299 Kč -

Deep Silence
267 Kč -

Lernzielkontrollen Biologie
671 Kč -

Homeric Greek: A Book For Beginners
882 Kč -

Kaiser Friedrichs Tochter Kunigunde
549 Kč -

Capital Intelectual y su relacion con el rendimiento
1380 Kč -

Investicii v APK Chechenskoj Respubliki
1115 Kč -

Omega Sec: Une romance Alpha Omega Grossesse masculine
307 Kč -

Jewish Liturgy as a Spiritual System
2905 Kč -

Creation Through Wisdom
3356 Kč -

Rigorous Development of Complex Fault-Tolerant Systems
1181 Kč -

Pilot clicker zelený
72 Kč -

Maximalism in Contemporary American Literature
1638 Kč -

Polymer Matrix Composites and Technology
5704 Kč -

Scalpel & Hatchet
387 Kč -
Super Yvonne. Tordus tout court vol 8
289 Kč -

When Research Goes Off the Rails
1608 Kč -

Sea Shenanigans Collection Two
392 Kč -

Theory and Methods in Social Research
950 Kč -

Homotopy Methods and Global Convergence
2194 Kč -

I CAN'T SLEEP, mit Online-Code
380 Kč -

Kaiser Julianus
610 Kč -

Practical Guide to Working in Theatre
770 Kč -

Advances in Aerogel Composites for Environmental Remediation
4620 Kč -

Red Shift
259 Kč
Darujte tuto knihu ještě dnes
- Objednejte knihu a zvolte Zaslat jako dárek.
- Obratem obdržíte darovací poukaz na knihu, který můžete ihned předat obdarovanému.
- Knihu zašleme na adresu obdarovaného, o nic se nestaráte.
Více informací o knize Modelling Nonlinear Economic Time Series
Nákupem získáte 558 bodů
 Anotace knihy

This book contains an extensive up-to-date overview of nonlinear time series models and their application to modelling economic relationships. It considers nonlinear models in stationary and nonstationary frameworks, and both parametric and nonparametric models are discussed. The book contains examples of nonlinear models in economic theory and presents the most common nonlinear time series models. Importantly, it shows the reader how to apply these models in practice. For this purpose, the building of various nonlinear models with its three stages of model building: specification, estimation and evaluation, is discussed in detail and is illustrated by several examples involving both economic and non-economic data. Since estimation of nonlinear time series models is carried out using numerical algorithms, the book contains a chapter on estimating parametric nonlinear models and another on estimating nonparametric ones. Forecasting is a major reason for building time series models, linear or nonlinear. The book contains a discussion on forecasting with nonlinear models, both parametric and nonparametric, and considers numerical techniques necessary for computing multi-period forecasts from them. The main focus of the book is on models of the conditional mean, but models of the conditional variance, mainly those of autoregressive conditional heteroskedasticity, receive attention as well. A separate chapter is devoted to state space models. As a whole, the book is an indispensable tool for researchers interested in nonlinear time series and is also suitable for teaching courses in econometrics and time series analysis.
Parametry knihy
Zařazení knihy Knihy v angličtině Economics, finance, business & management Economics Macroeconomics
5584 Kč
- Plný název: Modelling Nonlinear Economic Time Series
- Autor: Timo Terasvirta, Dag Tjostheim, Clive W. J. Granger
- Jazyk: Angličtina
- Vazba: Pevná
- Počet stran: 586
- EAN: 9780199587148
- ISBN: 0199587140
- ID: 04533586
- Nakladatelství: Oxford University Press
- Hmotnost: 982 g
- Rozměry: 241 × 164 × 35 mm
- Datum vydání: 15. December 2010
Oblíbené z jiného soudku
-
Manias, Panics, and Crashes
580 Kč -
Theory of Money and Credit
263 Kč -
Advanced Macroeconomics
3016 Kč -
Enlightened Economy
473 Kč -
Schaum's Outline of Macroeconomics
606 Kč -
Economics: A Very Short Introduction
231 Kč -
History of Money
311 Kč -
Philosophy of Money
833 Kč -
Contours of the World Economy 1-2030 AD
1572 Kč -

General Theory of Employment, Interest, and Money
914 Kč -

Economy of Words
863 Kč -

Born on Third Base
360 Kč -
General Theory of Employment Interest and Money
408 Kč -
Studies in the Byzantine Monetary Economy c.300-1450
1286 Kč -
Economics of Worldwide Stagflation
1097 Kč -
When Money Destroys Nations
332 Kč -
Macroeconomics, Global Edition
2302 Kč -
End The Fed
343 Kč -
Monetary Theory and the Trade Cycle
341 Kč -
Concise Guide to Macroeconomics, Second Edition
582 Kč -
Macroeconomics, Global Edition
2117 Kč -
Macroeconomics (European Edition)
2778 Kč -
Golden Fetters
1312 Kč -
Euro and the Battle of Ideas
564 Kč -
Money
711 Kč -
Does Capitalism Have a Future?
1191 Kč -
Great Escape
1328 Kč -
Macroeconomics
1853 Kč -
Program for Monetary Stability
335 Kč -
Reinventing Capitalism in the Age of Big Data
292 Kč -
Interest and Prices
3242 Kč -
Monetary Theory and Policy
2684 Kč -
Risk Topography
3020 Kč -
Blockchain Revolution
284 Kč -
Digital Gold
248 Kč -
Theory of Money & Credit
361 Kč -
Death of Money
292 Kč -
Great Escape
415 Kč -
Saving Capitalism
246 Kč -
Cartoon Introduction to Economics Vol 2
343 Kč -
Dollar Crisis, Causes, Consequence, Cures Revised and Updated edition
582 Kč -
All About Forex Trading
407 Kč -
Macroeconomics For Dummies - UK
375 Kč -
Cryptocurrency
285 Kč -
Modern Money Theory
2352 Kč -
Business Cycles
302 Kč -
General Theory of Employment, Interest, and Money
423 Kč -
Between Debt and the Devil
511 Kč -
History of Money
1218 Kč
Osobní odběr Praha, Brno a 48595 dalších
Copyright ©2008-26 nejlevnejsi-knihy.cz Všechna práva vyhrazenaSoukromíCookies

 Vrácení do měsíce
 571 999 099 (8-15.30h)
